No results found.
Try a different search term or browse the help topics below.
How to change your regular contributions
When your employer enrols you into a workplace pension with us, you will normally contribute a percentage of your salary to your pension. You will see this pension contribution reflected on your payslip. You can adjust the size of this percentage in your Smart Pension account.
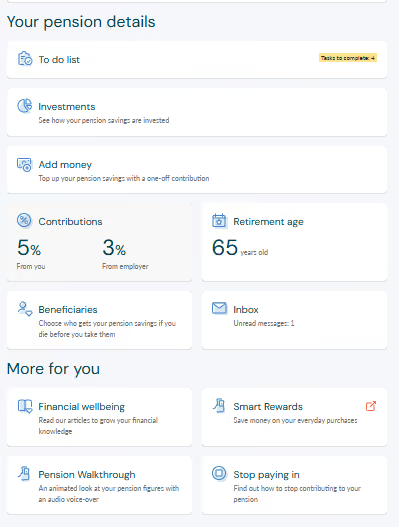
- Sign in to your account and click on Contributions on the 'Your pension' page. Here you can see the current percentage of your pensionable earnings that you and your employer put into your pension.
- Use the + or - buttons to change your contribution percentage.
- Select Update contribution to save your changes. The changes will be reflected in your next pay period.
What’s the minimum contribution that needs to be made?
Under standard UK automatic enrolment rules, you and your employer need to contribute a total of at least 8% of your salary to your pension.
If your employer contributes 3% (the minimum level currently required of them by law), your minimum contribution will be 5%, to make 8% in total.
If your employer matches your contributions to 4% or more, your minimum contribution will need to be 4%, totalling 8% when matched by your employer.
How to make a one-off contribution
You can make a one-off contribution to your pension whenever your financial circumstances allow, making it a helpful way to boost your pension. This kind of extra one-off contribution is known as an additional voluntary contribution (AVC).
There are currently two ways you can make an AVC.
1. Through your employer
Speak to your employer/payroll department and they’ll take your contribution out of your salary and let us know. You’ll see the contribution appear in your pot within six weeks of us receiving their payroll data.
2. From your personal bank account using your Smart Pension mobile app
Select Add money on the home screen and follow the instructions. Payments made this way will attract basic rate tax relief, which Smart Pension will claim on your behalf, enhancing your contribution even more.
Maximum contributions
There is a limit to the total amount that you can contribute to your pension each tax year. This is known as the annual allowance.
For the tax year 2026/27 the annual allowance is £60,000 across all of your pension arrangements. This covers all your contributions, your employer’s contributions, and any tax relief you may get. Once you go over this allowance, you will incur a tax charge, known as the annual allowance charge.
If you earn over £200,000 a year, or if you've already started to access any of your pension savings, your annual allowance may be different.
If you'd like more information on adjusting your pension contributions, we recommend talking with a financial adviser.
Smart Pension can only provide guidance and is not regulated to give financial advice. If you require professional advice, you can find support on the MoneyHelper website.